
Welcome!
My name is Maximilian Fuchs, I am an economist at Bruegel and former research fellow at Copenhagen Business School and the European Central Bank.
I am excited about research on financial markets and climate economics and their interactions with the financial system and the real economy.
Research
Yes. We estimate that the EU CBAM increased the adoption of carbon pricing in other countries by 17%. Read abstract
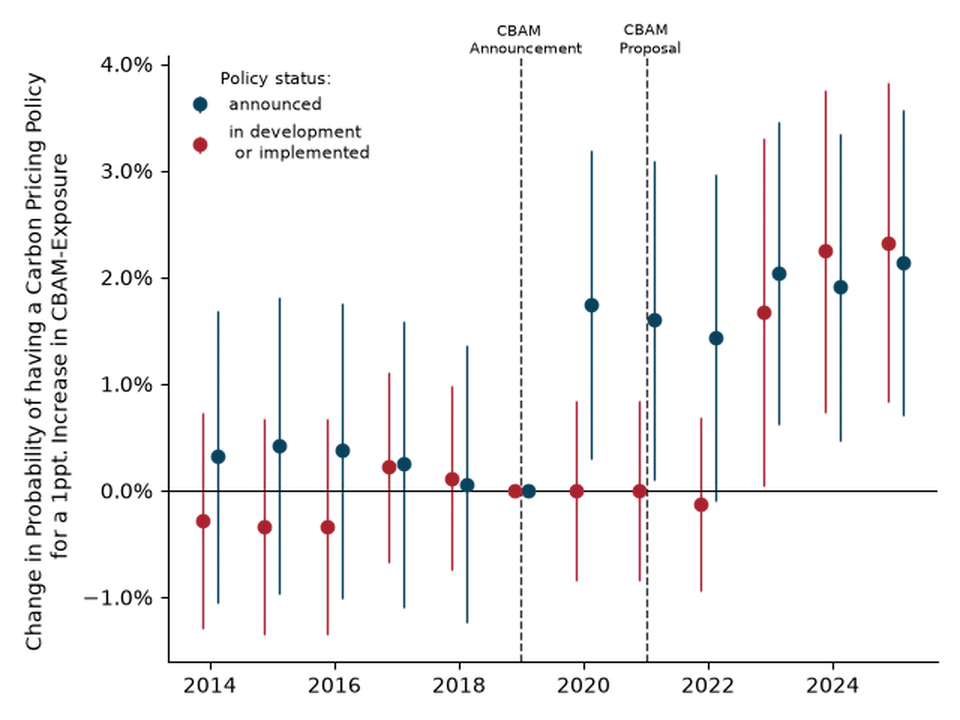
This paper provides a theoretical framework showing that the EU carbon border adjustment mechanism (CBAM) creates incentives for EU trading partners to adopt domestic carbon pricing. To test this prediction, we collect information on the evolution of carbon pricing mechanisms and construct a measure of CBAM-exposure based on trade data across 163 countries. We find that the introduction of the carbon border measure increases adoption rates of carbon pricing policies in countries with greater trade exposure. A one-percentage-point increase in CBAM-exposure raises the probability of adopting carbon pricing by 1.6 percentage points, a 17% increase on the pre-CBAM adoption rate. This effect concentrates among higher income countries consistent with lower income countries facing capacity constraints to implement similar mechanisms.
Journal of Financial Economics
The Carbon VIX is a market-based measure of carbon price uncertainty. We show it depresses firms' decarbonization investment. Read abstract
We study the effects of carbon price uncertainty on firms’ decisions to decarbonize their operations. We first use information on the pricing of options on emission allowances in the European Emissions Trading System to create the Carbon VIX, a market-based high-frequency measure of carbon price uncertainty. Carbon price uncertainty is high, varies substantially over time, and experiences persistent shocks around major climate policy events. To explore the effects of carbon price uncertainty on expected aggregate decarbonization investments, we analyze its effect on the stock returns of firms that help other businesses decarbonize. To identify these “carbon solution providers”, we extract common types of decarbonization investments from a large survey of firms, and then identify companies that offer the associated goods and services. We find that the stock returns of these carbon solution providers vary positively with carbon prices, but negatively with carbon price uncertainty. The effect of increases in carbon price uncertainty on our proxy for expected decarbonization investments is economically large and of similar magnitude as the effect of declines in carbon prices. These findings support predictions from real options theory that firms may delay investments in decarbonization when faced with uncertainty about the future costs of emissions.

A new firm-level dataset of EU ETS permit holdings. Many firms hold large excess permits to hedge carbon price uncertainty. Others disproportionally reduce their emissions. Read abstract
Based on administrative data, I construct a novel dataset of firm-level holdings of emission permits in the EU Emission Trading System. Emission permits take a sizable share on firms' balance sheets and a majority of firms hold large quantities of emission permits in excess of their emission levels. I find evidence that holders of excess permits retain permit holdings to hedge future shocks to carbon prices. Firms with excess holdings (1) trade less, (2) sell more permits when carbon price uncertainty is low, and (3) show smaller reductions in future emissions. These results are consistent with models of firms' permit trading and decarbonization behavior under risk aversion and uncertainty and provide empirical evidence that carbon price uncertainty leads to limited trading participation and excess cost of decarbonization.

Do banks price climate policy risk into their corporate loans? We find they do. But only when polluting borrowers face stringent climate policy. Read abstract
Using Euro area banks' credit register data, information on borrowers' greenhouse gas emissions and their countries' degree of climate policy action (CPA), we study whether banks price climate-related policy risk in their corporate loan portfolios. We find these risks are priced only when polluting borrowers face high levels of CPA. This effect is driven by loans originated after the adoption of the Paris Agreement and is more pronounced for long maturity loans. Benefiting from bank-level survey results, we show that this effect is larger in terms of scope and magnitude if loans are provided by green banks.
A draft is available upon request.

High-emission firms generate cash flows early as climate risks are more stringent in the future. Read abstract

ECB Occasional Paper Series
Stress-testing three transition pathways to net zero, and quantifying the financial risks for Euro-area firms, households and banks. Read abstract
Transition to a carbon-neutral economy is necessary to limit the negative impact of climate change and has become one of the world’s most urgent priorities. This paper assesses the impact of three potential transition pathways, differing in the timing and level of ambition of emissions’ reduction, and quantifies the associated investment needs, economic costs and financial risks for corporates, households and financial institutions in the euro area.
